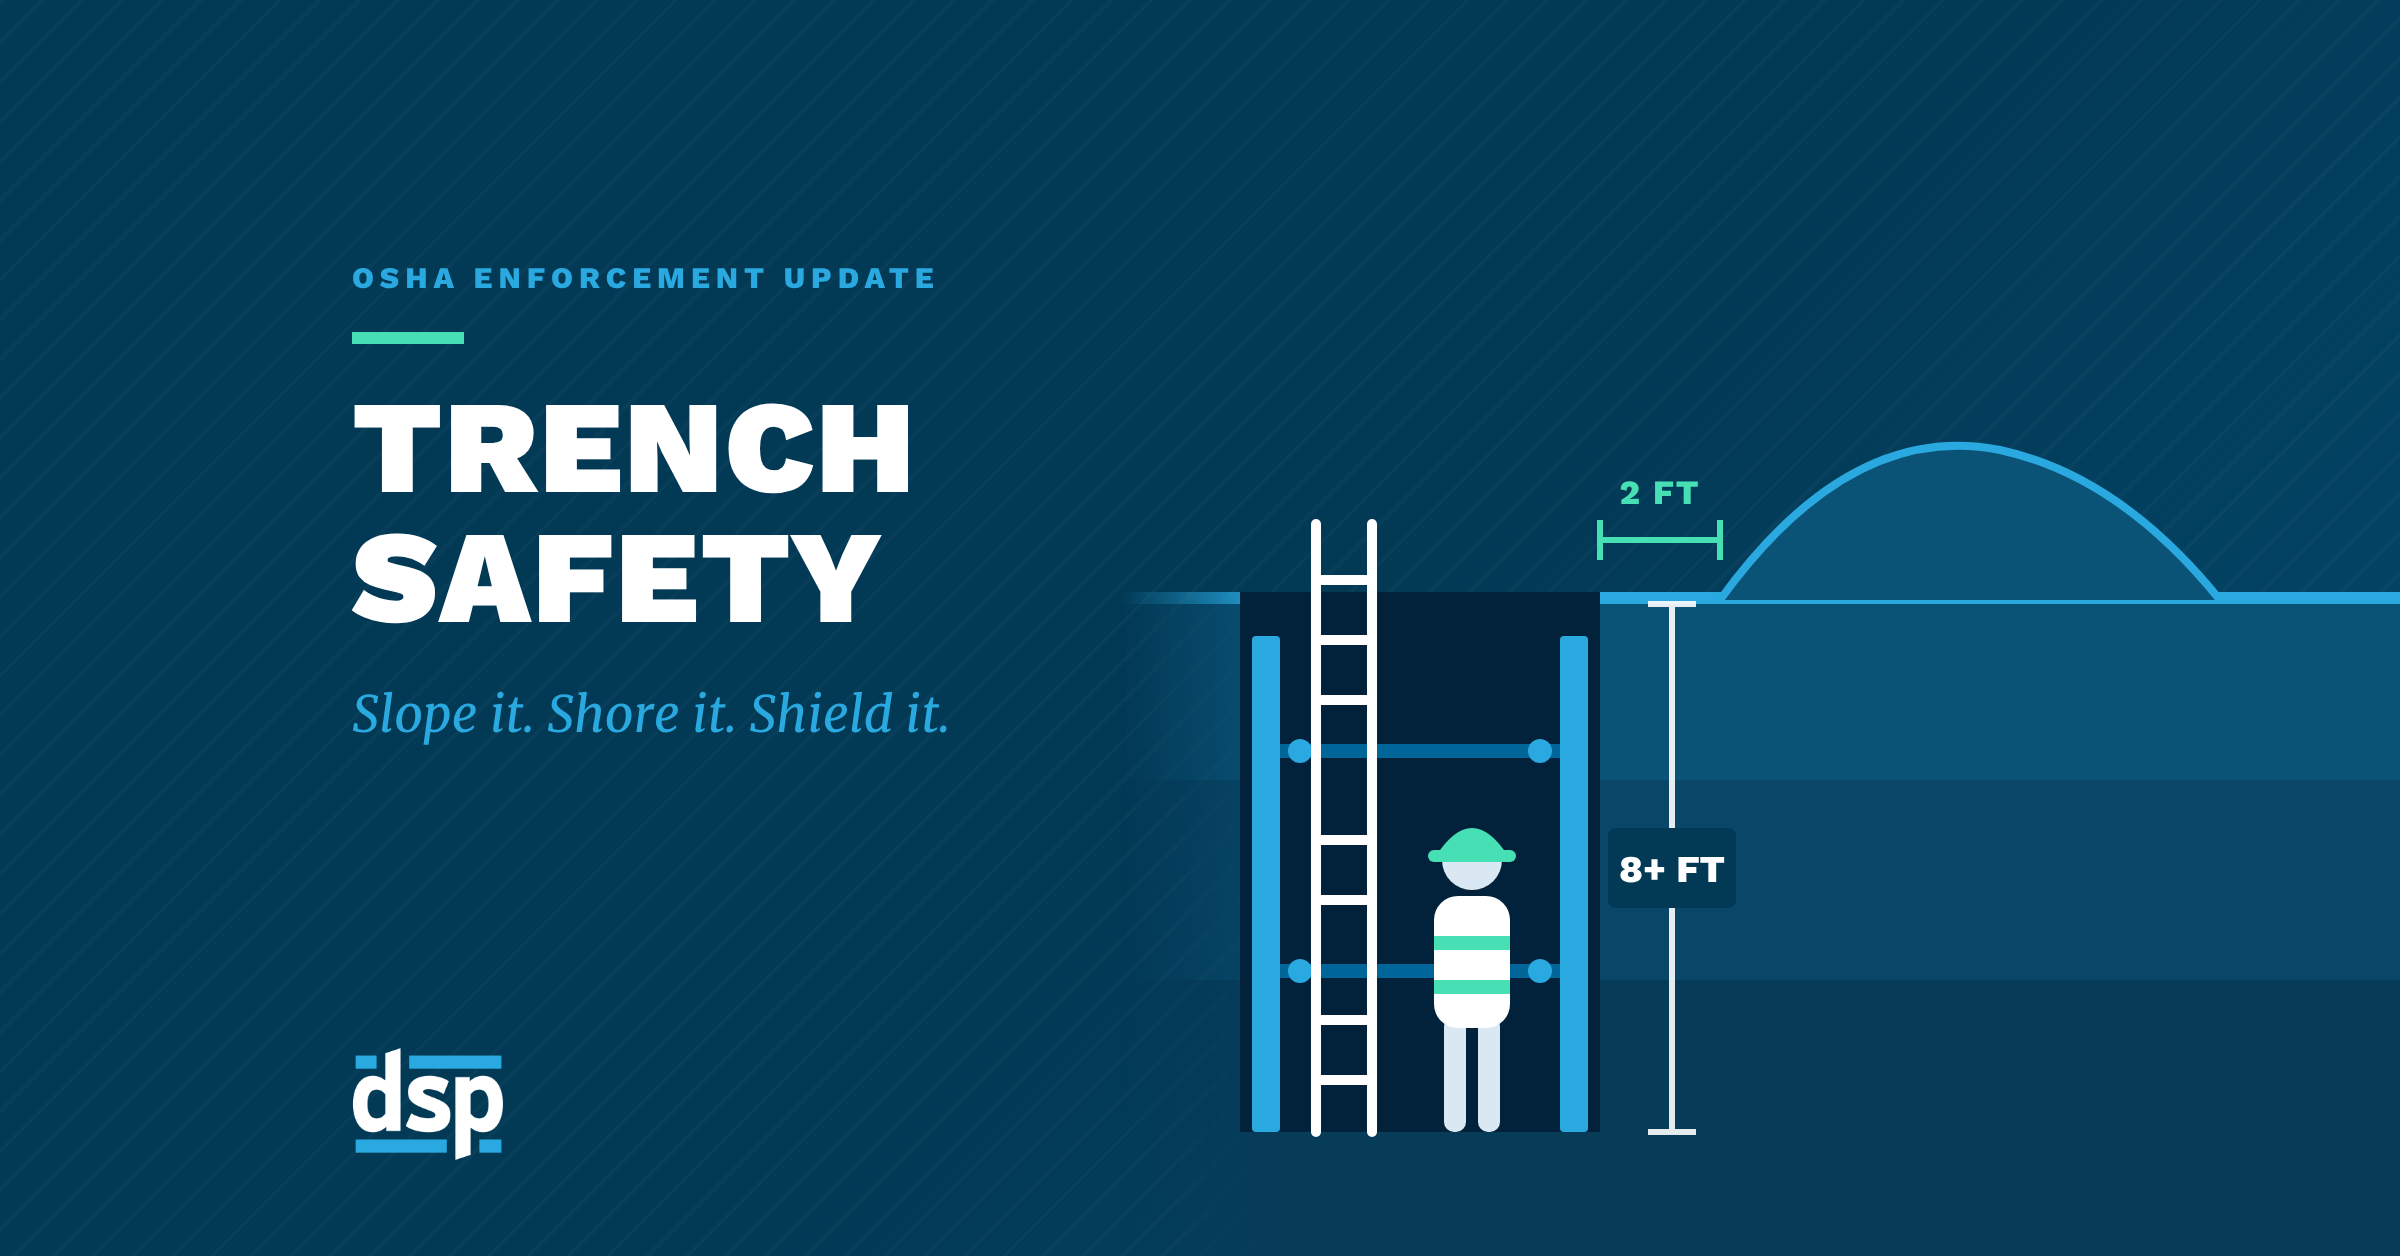
Trenching and excavation work remains one of the most hazardous jobs in construction, and OSHA is making sure contractors don't forget it. In October 2026, the U.S. Department of Labor proposed $380,664 in penalties against a utility contractor based in Frankfort, Illinois, after investigators found employees working in an unprotected trench more than eight feet deep.
Recent Posts
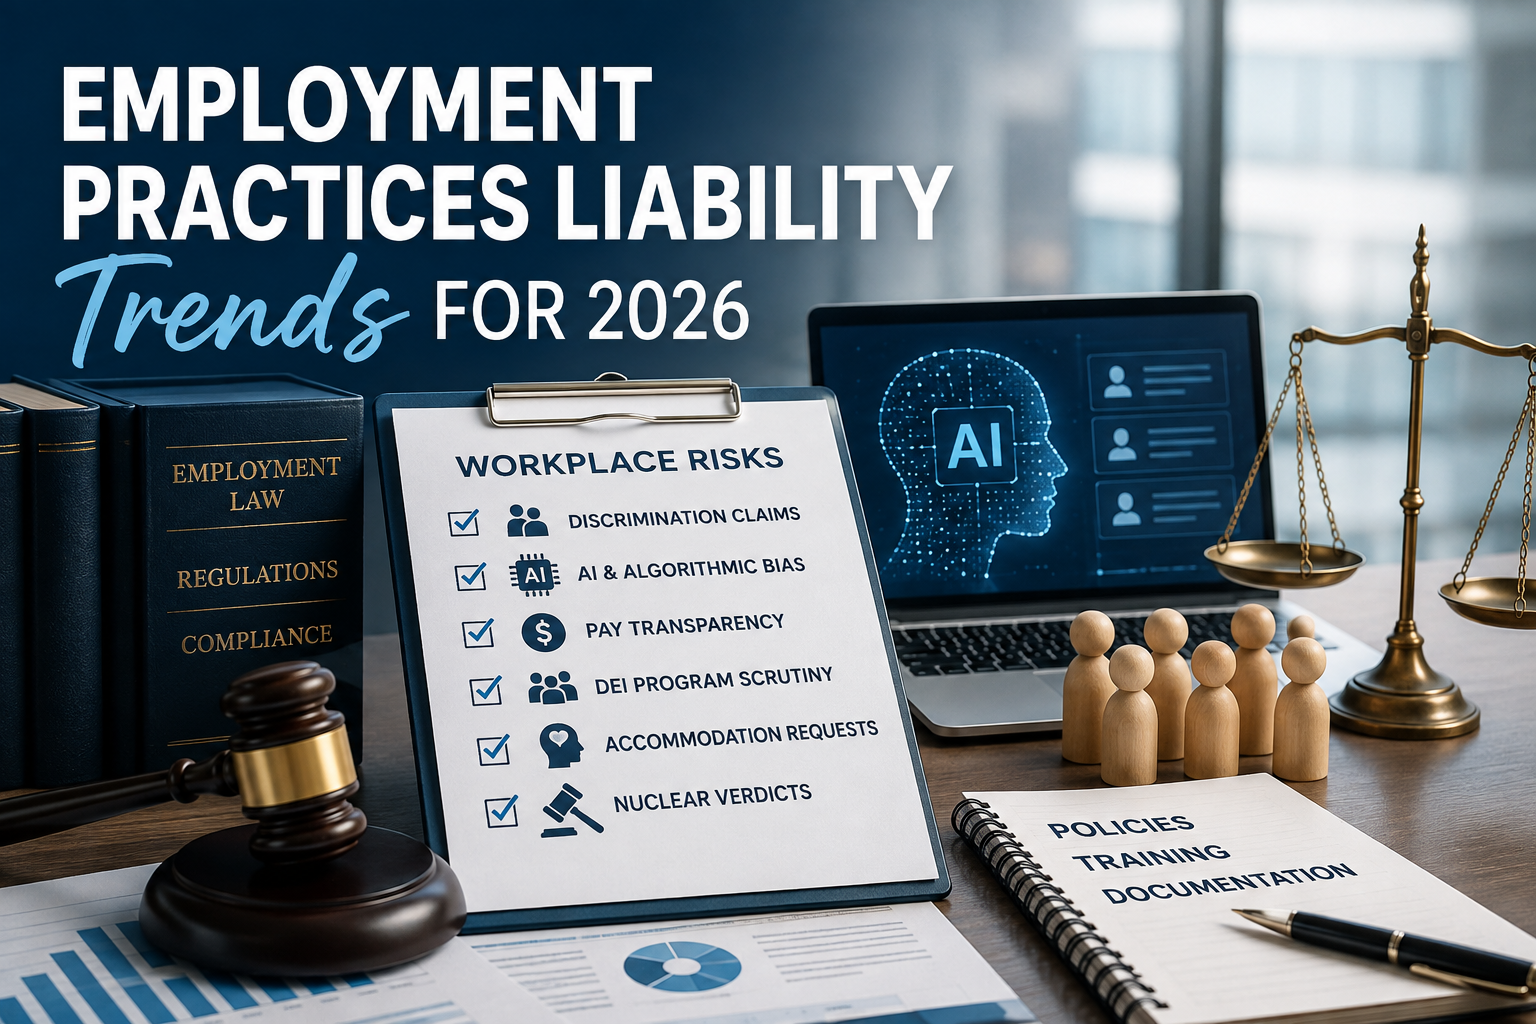
Employment practices liability risks are evolving as workplace regulations change, artificial intelligence becomes more integrated into HR decisions, and employees gain new protections. For employers, these changes can create greater exposure to discrimination claims, pay equity disputes, accommodation requests, and other employment-related litigation.
A recent Zurich report on employment practices litigation trends for 2026 highlights several developments businesses should be watching.
Most companies approach safety training the same way each year. They assign courses, send reminders, track completions, and move on. On paper, that process checks the box. But in practice, it often leaves a gap between completion and actual understanding.
That gap matters.
Here's something that stops me mid-conversation every time I bring it up with a business owner: If I told them they could start their own insurance company, keep the underwriting profit, and potentially save six figures a year, they'd think I was running a scam. But that's essentially what a captive is.
Most businesses renew their insurance program the same way each year.
Meet with their broker. Review the numbers. Negotiate a little. Move on.
But very few companies stop to ask a more important question:
How does our program actually compare to the rest of the market?
Not what one carrier thinks. Not what last year looked like.
What does the data say?
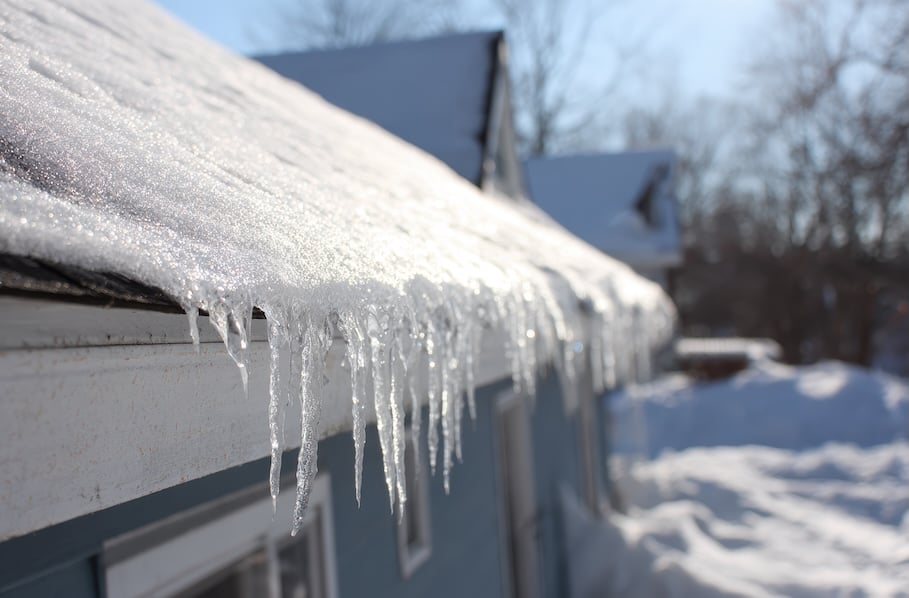
Winter is here, and with it comes one of the season’s biggest headaches for homeowners: ice dams. These ridges of ice form when warm air inside your home melts the snow on your roof, only for that melted snow to refreeze at the edges. Once that happens, the water behind the ice has nowhere to go. Eventually, it works its way under shingles and into your home, causing stains, leaks, warped materials, and costly frustration.
It’s a common winter issue in the Midwest, but the question we hear most often is simple: Does homeowners insurance cover this? In many cases, yes.
Insurance fraud isn’t just an industry problem, it’s a business problem. Fraud costs the U.S. an estimated $308 billion every year, with property and casualty fraud making up nearly $90 billion of that total. Those losses trickle down in the form of higher premiums, stricter terms, and challenges when it comes to securing coverage.

When it comes to business insurance in Texas, it’s definitely gotten tougher, especially for certain industries and locations. Carriers are tightening their underwriting, rates are rising, and some coverage lines are getting harder to secure altogether.
What's Making Business Insurance Harder to Get in Texas?
Weather-driven claims
Frequent hurricanes, hailstorms, and extreme heat have made Texas one of the most disaster-prone states. Commercial property carriers are responding by:
- Pulling back in high-risk areas
- Increasing deductibles for wind/hail
- Requiring more documentation or inspections
- Sometimes declining to quote at all
Fewer carriers, less competition
Some major insurers have reduced their appetite for commercial risks in Texas, particularly for:
- Construction
- Hospitality
- Real estate/lessors risk
- Coastal properties
This has shrunk the market and given the remaining carriers more pricing power.
Skyrocketing premiums
Rates are climbing across almost every line, especially commercial property, liability, auto, and umbrella. If your loss history isn’t clean or if you operate in a high-risk class, expect double-digit increases or stricter terms.
Legal environment
Texas has a reputation for high litigation frequency and big verdicts (especially in auto and general liability claims). This has caused umbrella and excess liability markets to recoil or raise rates sharply.
Surplus lines growth
Many businesses are being pushed into the excess & surplus market, especially for property and high-limit liability. These carriers aren’t admitted in Texas and may offer less flexible terms, but they’re increasingly the only option.
What Can Businesses Do?
- Work with an independent agent or broker who can access a wide range of markets (not just direct writers).
- Get ahead of your renewal - start marketing your policy 90+ days out, especially if you’ve had claims or operate in a tough class.
- Invest in risk management- carriers reward businesses that can demonstrate loss control, especially in safety, cybersecurity, and fleet management.
Yes, getting business insurance in Texas is harder than it used to be, especially for property-heavy, high-risk, or coastal operations. But with the right strategy, proactive planning, and a knowledgeable partner, it’s still very possible to secure solid protection at competitive rates.
Need help navigating the changing insurance landscape in Texas? Let’s talk about your options.
Most homeowners and companies know that property insurance rates are rising in this “hard” market over the past few years. Navigating co-insurance challenges shows that hard markets come with increased premiums, increased deductibles, and stricter coverage terms. Catastrophic property losses from weather events are becoming more frequent, and the dollar amounts per loss continue to rise, forcing insurance companies to re-evaluate their property insurance portfolios. At the same time, the cost to rebuild properties has increased dramatically due to rising construction costs for material and labor. Additionally, replacement costs on an insurance policy might be significantly higher than the market/retail value of the property. Now more than ever, property owners need to review their property coverage limits and make sure they are carrying adequate limits to avoid a co-insurance penalty, truly navigating co-insurance challenges.
In 2023, the U.S. trucking industry faced a series of overwhelming challenges, leading to the closure of nearly 88,000 trucking firms—around 10% of the nation’s total. The primary drivers were rising operational costs, especially as driver salaries and legal expenses soared. These factors, in turn, pushed up trucking insurance costs, creating a difficult cycle of shrinking profit margins and higher costs for goods transported by trucks. As these increased expenses trickled down, the impact was felt in prices for everyday goods, affecting both businesses and consumers alike. (Source: Legal System Abuse Hammers Truck Insurance)
